Trending Topics

 Trending
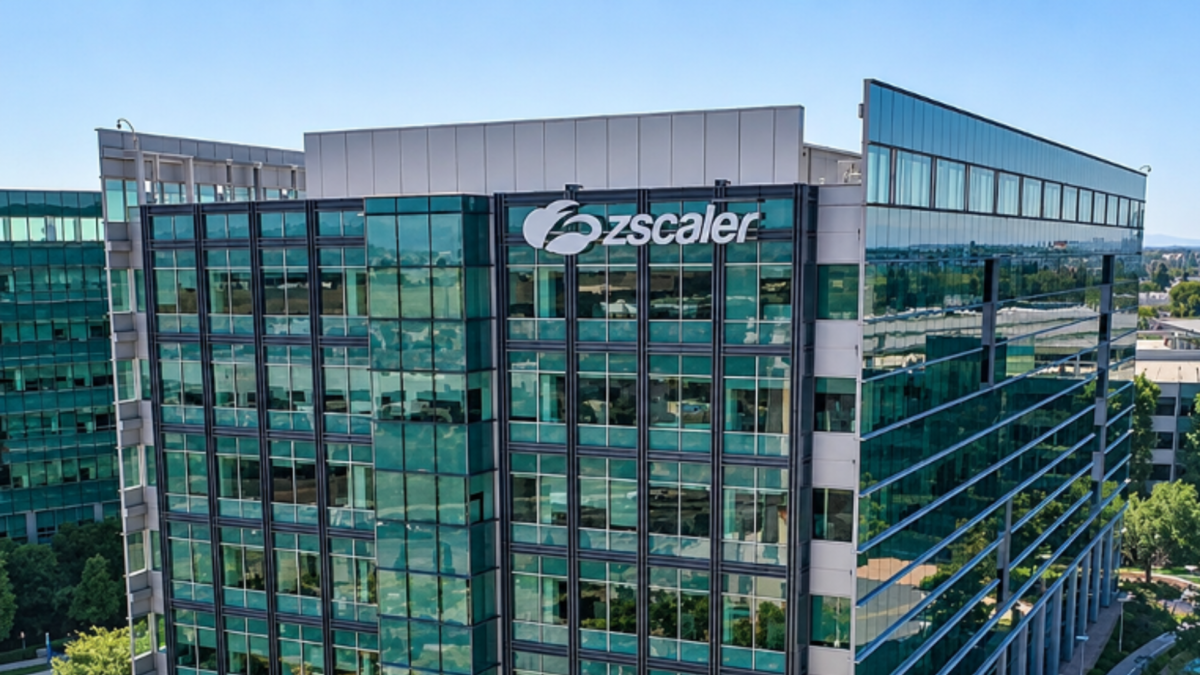
Zscaler’s Q1 FY27 results will test whether its AI ambitions are paying off

Zscaler will release its first-quarter fiscal 2027 results after US markets close on 2 December, followed by an earnings call at 1:30 pm Pacific Time. The announcement sets up a useful checkpoint: can the cybersecurity company turn its expanding AI security portfolio into sustained growth?
The immediate benchmark is already public.
At its October investor day, Zscaler reaffirmed guidance for quarterly revenue of $935 million to $939 million, approximately 19% year-on-year growth. It also expects adjusted earnings per share of $1.15 to $1.16 and an adjusted operating margin of approximately 23%. Those are management’s targets, not reported results or analyst consensus.
Zscaler faces a growth comparison worth unpacking
The previous quarter provides context.
Zscaler finished fiscal 2026 with quarterly revenue of $898.2 million, up 25%, while annual recurring revenue reached $3.771 billion, also up 25%.zscaler+1
However, acquisitions complicate the headline.
On its fourth-quarter call, management said annual recurring revenue growth was 20% excluding Red Canary. Net new recurring revenue grew 17% on that basis, compared with 24% including the acquisition. December’s discussion should help investors distinguish underlying demand from acquired growth.
That distinction is more significant than whether Zscaler clears the revenue bar by a few million dollars.
The full-year outlook is another reference point.
Zscaler expects a fiscal 2027 revenue of $3.908 billion to $3.938 billion, representing a growth of 16.6% to 17.5%. Whether management maintains or changes that range will help frame the quarter’s significance.
AI agents need controls. Will customers pay for them?
Zscaler’s pitch increasingly extends beyond securing employees. Its AI Broker and integrated Agent Registry are designed to govern agent communications and control access to enterprise resources.
As we explored in our analysis of AI agents as privileged insiders, these systems access data, invoke tools, and trigger workflows. The security challenge follows their authority, not simply their number.
The broader AI governance gap gives that proposition relevance. It does not, by itself, establish commercial traction.
On the call, the useful evidence would be paid adoption, larger customer commitments, and identifiable contributions from newer products. Product launches explain what companies can sell. The numbers should offer a clearer indication of what customers are buying.
About The Author
Kihara Kimachia
NEXT UP