Trending Topics

 Trending
Your finance software has spent decades waiting to be asked

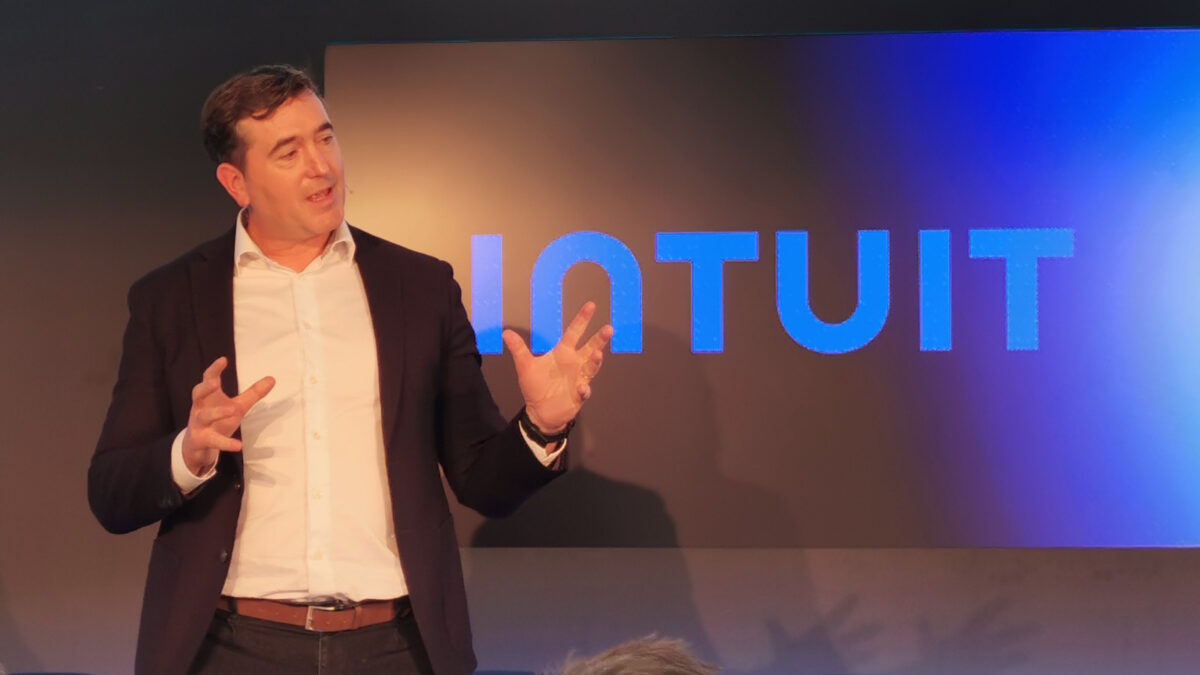
For decades, financial software has passively waited for user commands, but the rise of embedded AI is transforming these tools from static systems of record into proactive systems of action. Here, Ciarán Quilty, Senior Vice President of International at Intuit, explores how intelligent automation can anticipate business needs and streamline routine administrative work while keeping critical decisions firmly under human oversight.
Financial software has one remarkable personality trait: it is extraordinarily patient. It can hold the details of an overdue invoice for 90 days without a murmur. It can contain the information needed to spot a deteriorating cash position, yet say nothing until somebody thinks to run a report. The information may have been there all along. The system was simply waiting to be asked.
That is how a lot of business software has worked for decades. We have made it faster, moved it to the cloud and wrapped it in dashboards, but the basic contract has remained largely unchanged. A person notices something, a person goes looking, a person acts. The software keeps the record.
AI is starting to rewrite that contract, and I don’t think our industry always describes the change very well. Much of the conversation is about speed: categorise the transaction faster, draft the reminder email faster, produce the report faster. Speed is welcome, but the more interesting development is that financial systems are becoming capable of identifying what needs attention without waiting for someone to ask.
The opportunity is to build technology that understands what is happening across a business, anticipates what needs attention and takes on appropriate work while, crucially, keeping people in control of the decision making.
From system of record to system of action
If you buy or manage business technology, it helps to think of this in layers. The system of record stores what happened. The reporting layer tells you what happened, provided you ask the right question. What is emerging now is a third layer that can monitor financial activity, identify what needs attention, flag it and take action with approval.
Nobody starts a company because they dream of chasing invoices. Yet the more successful a business becomes, the more of its owner’s week can disappear into the administration that keeps it running. Software that helps people do that work faster only goes so far. Software that takes routine work off their plate gives them time to focus elsewhere.
Consider invoicing. Traditionally, someone prepares the invoice, sends it, checks whether it has been paid and follows up if it hasn’t. Each step may be supported by software, but the responsibility for moving the process forward often remains with a person.
AI is beginning to change that. Financial systems can increasingly use information the business already holds to prepare invoices, monitor payment status and initiate follow-up processes under agreed rules. Instead of remembering each step, the business owner can focus on the exceptions that need their attention.
The same principle applies to reporting. Rather than assembling information manually, businesses can increasingly ask questions about their financial position and explore future cash-flow scenarios using data already held across their systems.
For professional services firms like those in accountancy, the opportunity extends across entire client portfolios. Instead of opening individual files to identify what needs attention, technology can surface unusual patterns and potential issues for review. Firms can also standardise recurring processes and apply consistent working practices across clients.
None of these capabilities removes the need for reliable data or appropriate oversight. But they represent a different relationship with financial technology.
Software that once waited for instructions is increasingly able to identify, anticipate and support action. The value isn’t simply that work gets done faster. It’s that businesses can spend less time managing routine processes and more time responding to what matters.
The real constraint is trust
The shift towards more proactive financial systems raises an important question: how can businesses give technology more responsibility while remaining in control?
The answer lies partly in how AI is built into the software. There is a difference between asking a general-purpose AI assistant a financial question and using intelligence embedded within a system that already understands a business’s data.
The latter can draw on relevant financial data, established rules and specialist expertise to support more reliable outcomes. It can also work within existing processes, preparing information for review and carrying out permitted tasks without requiring someone to manage every step.
But greater automation should not mean unrestricted autonomy. Businesses need to understand what a system is doing, which actions require their approval and how they can review or correct its work. Trust comes from giving technology more responsibility within clear boundaries, rather than asking people to surrender control.
In enterprise technology, trust isn’t a feeling. It’s a set of properties. A trustworthy system operates within defined permissions, uses only information it is authorised to access and maintains a record of its actions.
That may sound less exciting than a demonstration of an autonomous AI agent. It is also what determines whether the technology can be used responsibly in a real business.
The distinction matters because autonomy in finance should not mean taking people out of consequential decisions. AI can help identify a potential cash shortfall before it happens or surface an unusual transaction for an accountant to investigate. But deciding what to do with that information still requires human judgement.
Financial AI is not infallible. The more responsibility we give these systems, the more deliberate we need to be about the boundaries set.
The next generation of finance software should earn our trust
After decades of software that waits for instructions, we have an opportunity to expect more from the systems businesses rely on.
Businesses evaluating financial AI should look beyond how quickly it produces an answer or how many tasks it can automate. They need to understand what the technology can do independently, which actions require approval and how its outputs can be checked.
They should also ask whether the intelligence works within existing financial processes or creates another tool employees must learn and manage. And, ultimately, whether it improves something that matters to the business: getting paid sooner, understanding cash flow, reducing avoidable errors or helping predict future financial outcomes.
None of this means handing the finance function to a machine. It means expecting technology to take on more of the work while people retain the ability to question, correct and decide.
After decades of very patient software, I think we have earned that.
You might also be interested
About The Author

Ricardo Oliveira
NEXT UP